About & Why This Exists
Everywhere you turn, the message seems to be the same: homes cost too much, buying is out of reach, and the dream will have to wait. I don't want that message to make your decision for you. The American Dream Project exists to replace discouragement with understanding, help you explore your options, and build a realistic path toward a place of your own.
Meet Roman
I'm Roman Svyatetskiy, a REALTOR® and Mortgage Loan Originator serving San Antonio and Central Texas. I hold a Texas real estate license (TREC #713126) and a mortgage loan originator license (NMLS #2777337), with real estate services through JPAR® San Antonio and mortgage services through NEXA Mortgage.
Seeing a first-time buyer finally receive the keys to a place of their own is what drives me. That passion has led me to invest in the education and licensing needed to serve people on both sides of the transaction: finding the home and understanding how to finance it. I especially want to help people who have counted themselves out before learning what might be possible.
My faith shapes how I serve: with honesty, patience, and respect for the responsibility a family is placing in my hands. I believe a home can be a foundation for stability, belonging, and stronger communities. My mission is to serve my local community through education and help families take informed steps toward the door of their first home.
The American Dream Project puts that mission into practice. Learn without pressure, ask the questions that matter to you, and understand your numbers before making a commitment. If buying isn't the right step yet, we'll talk honestly about what preparation could look like.
Roman Svyatetskiy · By God's Strength
Look beyond the headlines
Affordability deserves an honest conversation, not a quick dismissal. But a discouraging headline is not a personal assessment of your situation. Before deciding that buying is impossible, let's look at the whole picture together.
Texas buyers have gained more choice and negotiating room as inventory has risen from the tight conditions of the pandemic market, although opportunities vary by neighborhood and property. Texas Real Estate Research Center, Summer 2026.
An interest rate is one part of the decision, not the whole decision. We can look together at the purchase price, potential seller concessions, available loan options, cash needed to close, and the complete monthly payment. The goal is not simply to get you approved; it is to help you understand whether the home fits your life and budget.
Assistance is not always limited to a first purchase: TSAHC offers programs for eligible first-time and repeat buyers, including help with down payment and closing costs. Eligibility, availability, and repayment terms vary, so the details matter. Explore TSAHC homebuyer assistance.
Sometimes the missing piece isn't a perfect market. It's knowing which questions to ask and which opportunities are worth exploring. That is where education can change the conversation.
Why building equity matters
In the Federal Reserve's 2022 survey, median net worth was $396,200 for homeowner families and $10,400 for families classified as “renter or other”: a gap of roughly 38 to 1. Federal Reserve Survey of Consumer Finances.
This compares total net worth, not just home equity. It does not mean buying a home alone creates that gap or guarantees a financial return; families also differ in income, age, savings, and other circumstances.
For me, the point is not to pressure anyone into buying. It is to make sure people don't dismiss the possibility of ownership before understanding what it could mean for their future.
Median family net worth, 2022. Historical national data, not a prediction of individual results.
More than a monthly payment
A primary residence does not have to produce rental income to have value. Your equity is the home's current value minus the mortgage debt secured by it. CFPB mortgage definitions.
With a typical amortizing mortgage, part of each payment reduces the principal you owe. That principal reduction builds equity; the portion paid toward interest does not. Taxes, insurance, maintenance, and other ownership costs also need a place in your budget. How mortgage payments work.
I think of principal repayment as a disciplined way to set money aside in something you own. But a home is not a savings account: equity is not readily available cash, and accessing it usually means selling or borrowing against the property. Market appreciation can add equity, but inflation does not guarantee a higher home value, and prices can fall.
Waiting can be the right decision when your finances need more preparation. My concern is when discouragement alone keeps a ready buyer from exploring ownership and the chance to begin building equity. Let's make that decision with knowledge and a plan, not fear.
How it works
Pick the entry point that fits where you are. Everything is honest education first — buying with me is a choice you make later, only if it makes sense.
01
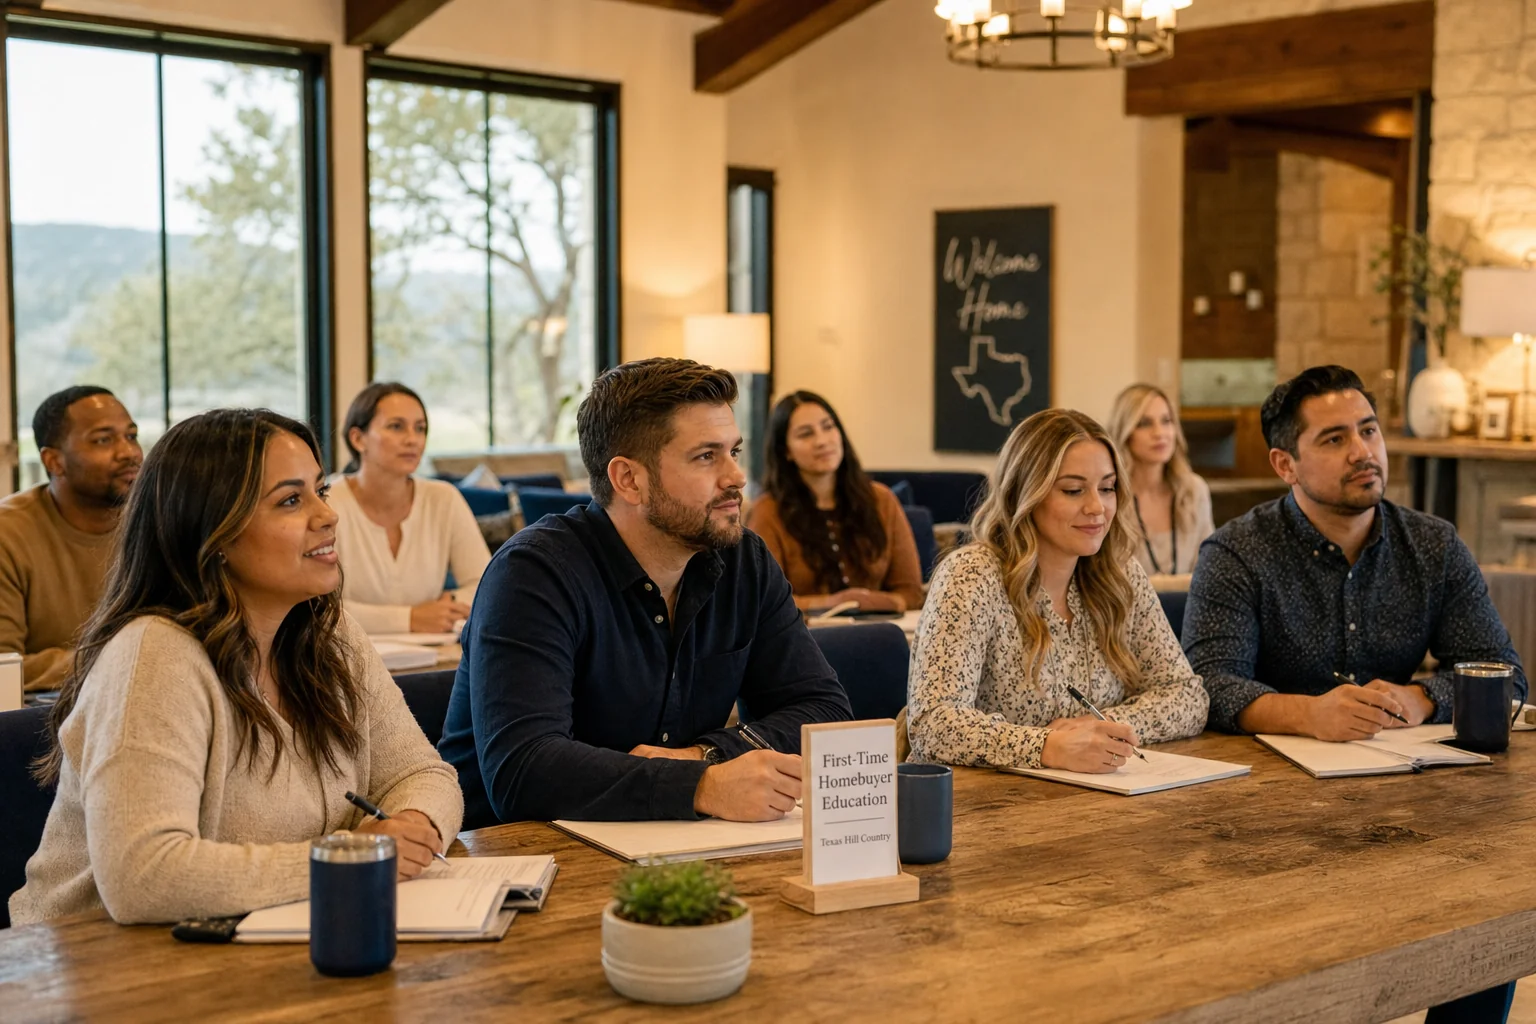
A 90-minute live session that walks through the whole process — pre-approval, loan programs, offers, inspections, closing. You leave with a real understanding of the game before you play it.
See dates & register →02
Private, 45 minutes, no cost. Bring your actual situation — income, credit, timeline, questions — and we'll map what a realistic path forward looks like. If now isn't the right time, I'll tell you.
Book your time →03
Checklists, calculators, program guides — all downloadable at no cost. Learn on your own timeline. Come back when you have questions.
Browse resources →Why the dual license actually matters
Real estate and mortgage lending are different specialties. An agent's day-to-day work centers on properties, negotiation, and contracts; a mortgage professional's centers on financing and qualification. Even dedicated professionals may not work with every detail of the other side. That is a difference in focus, not a lack of care.
When those two sides aren't fully connected, questions about financing, concessions, contract terms, and deadlines can create friction. My goal in holding both licenses is to help connect those conversations, explain how one decision affects another, and keep the path forward clear while working with everyone involved.
My passion for seeing first-time buyers receive their keys is why I put in the extra work in education and licensing. I want to provide better service, help people explore more possibilities, and give those who think they cannot buy a home a thoughtful, informed place to start.
Come to a class. Book a call. Or just start reading.